
Thinking About Tapping Into Your 401(k) To Buy a Home in Phoenix? Read This First.
Lately, headlines have floated an eye-catching idea about tapping into your 401(k) to cover a down payment on a home. Maybe you’ve caught the buzz and wondered whether that money could get you into a home faster here in the Valley, especially with affordability as tough as it is.
Here’s what you need to remember. Pulling from your retirement savings is a big decision, so take time to weigh all your options first and be sure to talk with a financial expert before you do anything.
Why Dipping into a 401(k) Can Be Tempting
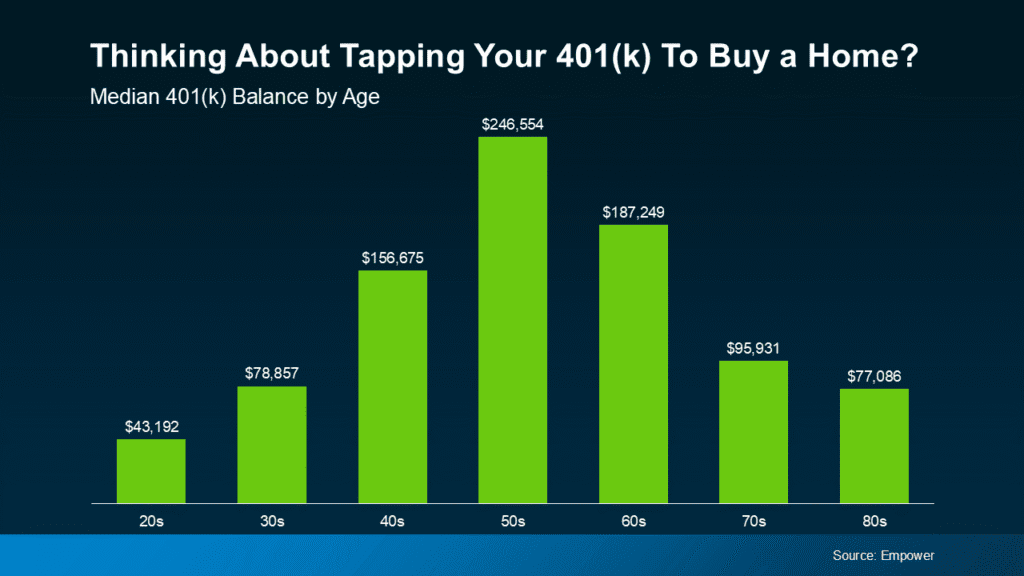
Data from Empower shows many Americans have built up considerable retirement savings. The median 401(k) amount for anyone in their 40s-60s is six figures (see graph below):
And when you’ve got a good chunk saved and your dream home is right there, reaching for it can feel like an easy call. That’s especially true in metro Phoenix right now. The median single-family home sold for right around $470,000 this August, essentially flat from July and only about 2% below where it stood a year ago, according to Cromford Report data. That kind of price tag makes a lump sum sitting in a 401(k) look very appealing, very fast.
But dipping into your retirement savings to buy a home could cost you a penalty and set back your finances later on. That’s why it’s a good idea to explore other options for your down payment first. As Redfin says:
“If you’re struggling to save enough for a down payment, you may be wondering if tapping into your 401(k) is the right option. While it’s possible, doing so comes with significant risks, like early withdrawal penalties and lost investment growth.”
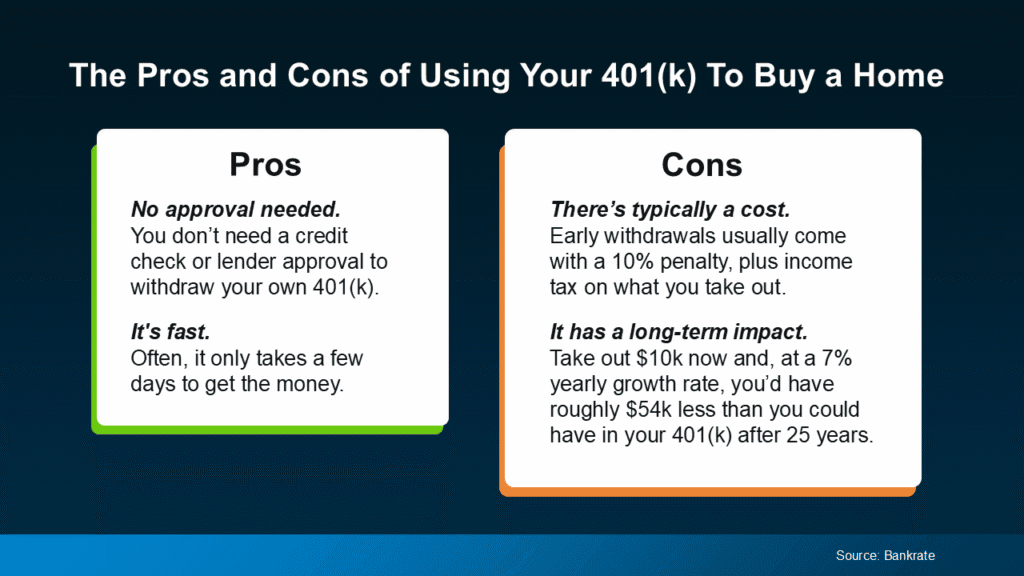
Before you decide, have a financial advisor help you compare the upsides to the risks. Bankrate points to a few of each (see visual):
Other Options Worth Exploring First
Your 401(k) isn’t the only way to finance a home purchase, and here in Arizona you actually have more local tools than most buyers realize. Redfin outlines a couple of national options worth looking into:
- Low and No-Down Payment Loans: FHA loans, for example, allow qualified buyers to put down as little as 3.5% of the home’s price, depending on their credit scores. VA-eligible buyers, including many connected to Luke Air Force Base, may qualify for zero-down financing and can often skip this decision altogether.
- Down Payment Assistance Programs: Many national and local programs can help reduce what you pay toward your down payment or closing costs.
In Maricopa County specifically, two programs come up often in these conversations:
- Home in Five Advantage: A Maricopa County program offering down payment and closing cost assistance to qualified buyers, structured as a second mortgage rather than a withdrawal from your future.
- HOME Plus: A statewide Arizona Department of Housing program offering similar assistance for eligible buyers across the Valley.
Both come with their own income limits, purchase price caps, and credit requirements, which shift periodically, so the right move is to run your numbers against current guidelines rather than assume last year’s limits still apply. That’s a conversation worth having before you look at your 401(k) as Plan A.
It’s also worth remembering that Phoenix is really a collection of markets, not one market. What it takes to get into a home in Scottsdale or Paradise Valley looks different than what it takes in Buckeye, Surprise, Goodyear, or Apache Junction, where entry points tend to be more accessible. Your down payment strategy should reflect where you’re actually buying, not a national average.
Make a Plan Before You Make a Move
No matter which route you take, talk with a financial expert first. The buyers who come out ahead build a solid plan with the right professionals before starting their journey to homeownership. As NerdWallet puts it:
“Even if you’re convinced a 401(k) loan is the way to go, it’s important to understand the risks at the outset.”
Bottom Line
Affordability is definitely a challenge in the Valley right now, but that doesn’t mean tapping your 401(k) is your only way in if you want to buy.
If you’re considering using your 401(k) savings for a down payment, weigh all your options, including local programs like Home in Five Advantage and HOME Plus, and talk with a trusted advisor before you make any decisions. Reach out and we’ll map out a plan that fits your goals, your timeline, and your budget in the Greater Phoenix market.
Before you touch your retirement savings, talk to someone who knows the Phoenix market.
Tapping your 401(k) to buy a home is a decision that follows you for years, not just to closing. Before you make that call, let’s look at what you actually qualify for, including local down payment assistance programs most buyers never hear about.
Schedule your free 30-minute Mortgage Strategy Call and get a clear, honest plan built around your goals, your budget, and the Greater Phoenix market.
👉 Book your call now: kevinbrierton.com/call