Kevin Brierton - Branch Manager CLA, CMPS, NMLS 599873
Your No Excuse Lender
As YOUR NO EXCUSE LENDER, we provide clear communication, great follow-up, and on-time closings—no excuses. Our mission is to empower families and partners with a more confident mortgage experience. We’re not just here for the pre-approval and loan process; we’re committed to guiding our clients for the next 30 years, helping them grow wealth through smart mortgage strategies
Clear. Consistent. On-Time. No Excuses
Kevin Brierton Team
The Kevin Brieton Team is committed to helping our clients grow their wealth and better understand their holistic financial situation, not just to give them debt.
Whether you need a Conventional loan, FHA loan, VA loan, Jumbo loan, Reverse Mortgage, Renovation loan, Home Equity Lines of Credit ( HELOC ) or a non QM Portfolio loan we are here to educate and serve you! Learn more about Loan Types

You Deserve More.... You Deserve a No Excuse Mortgage Process
Are you sick of excuses from lenders & banks? We are too!
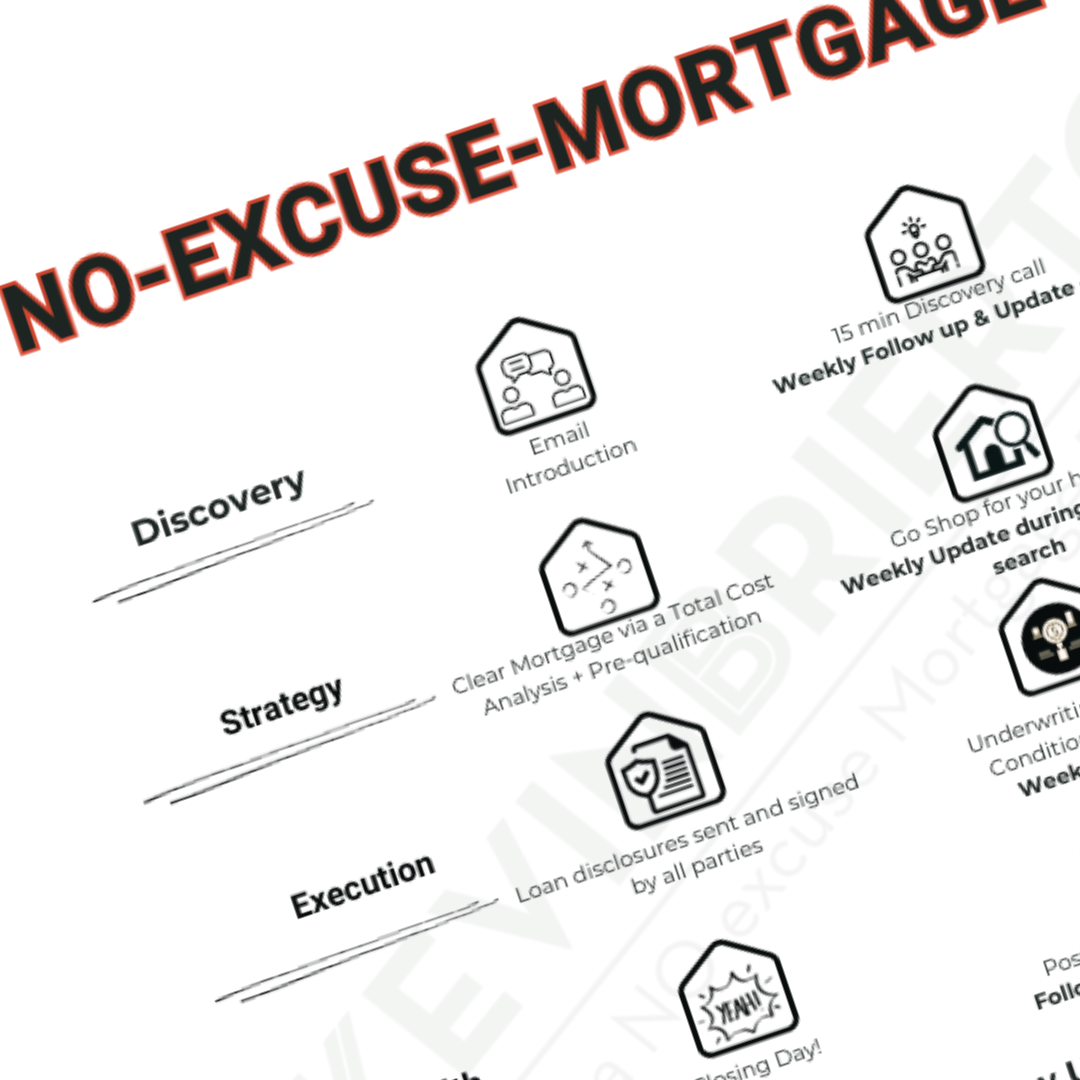
We have built a No Excuse Mortgage Process backed by a No Excuse Promise designed to provide an process that provides clear communication, great follow up and on time closings with no excuses.

Families Not Files
Our loan files are titled FAMILIES rather than "files" because the team understands that a family trusts us behind all that paperwork.
We work towards getting these families a place to call home now and into the future. Kevin Brierton Team is here to create lifelong clients with our world-class services.
FREE Mortgage Payment Calculator & Mortgage Rate Updates

The True ROI of Refinancing: More Than Simply a Lower Rate
Most people look at refinancing through one lens: “Can I lower my interest rate?” That matters, but it’s not the full story. The real return on refinancing is not always found in the rate. It’s found in what the refinance allows you to do with your cash flow, liquidity, debt structure, and long-term wealth plan….

Lower Asking Prices Are a Win for Today’s Buyers
If affordability has been the biggest thing standing between you and a home, there’s a little good news. Asking prices have started to come down. The typical seller listed their house for a median of $429,500 in May. That’s 2.4% lower than a year ago, according to Realtor.com. On its own, that won’t transform what you…

The Jobs Report Came In Hot — And the Market Felt It Immediately
FOR THE WEEK OF JUNE 8, 2026 QUOTE OF THE WEEK “The best way to predict the future is to create it.” — Peter Drucker, Management consultant, educator, and author NATIONAL MARKET UPDATE Inventory continued to exceed, year-ago levels, giving buyers more options even as the pace of growth has slowed. Homes are now selling…

Could Moving a Bit Further Out Change Everything About Your Budget?
Whether you’re dreaming about buying your first home or wondering if it’s time to move on from the one you’re in, affordability is probably weighing on your mind. Home prices are still high in many markets, and even though things have improved a bit over the past year, making the numbers work can still feel like a…

The Mid-Year Housing Market Update: Why Forecasts Changed in 2026
If the housing market feels confusing right now, you’re not alone. Mortgage rates have risen. Home sales haven’t picked up like expected. And many buyers and sellers are wondering when things are going to feel easier or be more affordable. The truth is: a lot changed over the first half of this year. Back at the…

Less House, More Home: Why Smaller Homes Are Paying Off for Today’s Buyers
You started shopping with a specific mental image of your future home in your mind. Then the houses in your budget came in smaller than you pictured. That’s the reality for a lot of buyers right now. Affordability is tight. But don’t let that discourage you. Going smaller might actually be a smart play in…

Native American Section 184 vs. VA Loan: Which Is Right for You?
Section 184 vs. VA Loan: Which Is Right for You? | Kevin Brierton If you’re a Native American homebuyer — or a loan officer working with one — you may have more options than you realize. Two of the strongest government-backed programs available today are the Section 184 Indian Home Loan Guarantee (administered by HUD)…

Sellers Are Pricing to Sell — And Inventory Is Rising. Here’s What That Means for Buyers Right Now.
For the week of June 1, 2026 QUOTE OF THE WEEK “The problem with the future is that it keeps turning into the present.”—Bill Watterson, American cartoonist NATIONAL MARKET UPDATE Inventory continued to build, with the number of homes for sale remaining above year-ago levels. New listings also increased compared to last year, giving buyers more…

VA Loan vs. Conventional Loan: Which One Is Right for You?
If you’re a Veteran or active duty service member shopping for a home, you’ve probably heard that you have access to a VA loan. What’s less clear is whether you should actually use it, or whether a conventional loan might make more sense for your situation. The honest answer is that for most Veterans, the…
Contact us today!
Reach out to learn how we can help you and your family grow your wealth, make smart decisions, and save money.